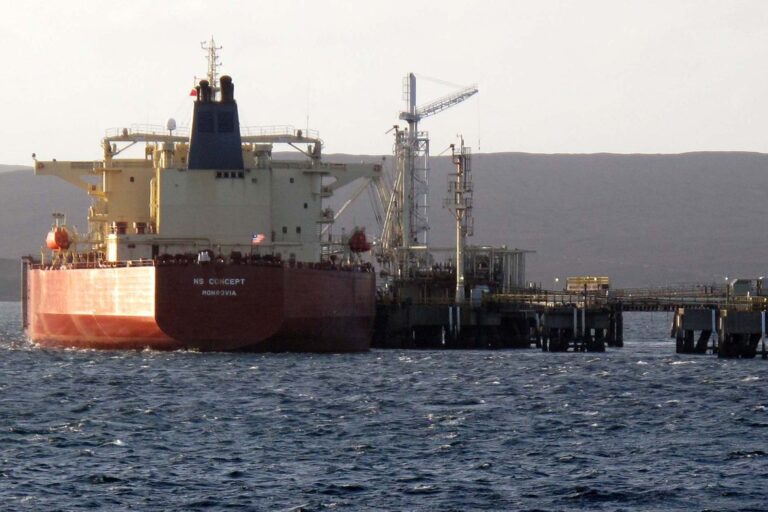
Japan has recorded a widening trade deficit as soaring oil import costs, driven by escalating conflicts in the Middle East, force industrial economies to pay record premiums for energy.
The Strategic Weight of the Region
The Middle East remains a geo-political region defined by vast petroleum reserves that have influenced regional and global politics since the early 20th century. Situated at the intersection of Africa, Europe, and Asia, the area has long been recognized as a region of great strategic importance for millennia due to its core Abrahamic religions and historical role as a cradle of civilization.
A group of Middle Eastern countries located along the Persian Gulf, commonly called the Gulf Arab states, hold vast reserves of petroleum that serve as a critical economic resource. These reserves are concentrated in nations such as Saudi Arabia, which is the largest Middle Eastern country by area, alongside Egypt and Iran, which rank among the three most populous nations in the region.
The history of the Middle East is among the richest ever recorded, having been the first region outside of Africa to be settled by modern humans. This historical depth underpins the current geopolitical tension, where the bulk of Middle Eastern countries are part of the Arab world, yet political borders now demarcate the region rather than just continental boundaries.
The Mechanics of a Risk Premium
Benchmark Brent futures have recently traded above $100 per barrel, reflecting the volatility inherent in global energy markets. A barrel of dated Brent crude scheduled for delivery in the next month is currently trading at more than $130, a figure that includes a nearly $25 risk premium on top of fair value.
This premium exists because physical prices remain elevated while escalation threatens supply and near-record-low global inventories fuel strong restocking demand. Physical prices are driven by the fear that Iran or the Houthis could target oil infrastructure in the region, including ports, pipelines, and oil fields.
Global oil inventories are at near-record lows, which fuels strong restocking demand despite the recovery in exports from the Middle East. The sensitivity of global stocks and bonds to oil prices has increased demand for oil as a portfolio hedge, further sustaining high costs even as supply recovers.
The Houthis, an Iran-backed armed movement designated a terrorist organisation by the US, operate within Yemen where a civil war is raging between the internationally recognized government and the Tehran-backed forces. Persian Gulf oil exports include an estimated four million barrels per day of ‘dark’ exports with transponders turned off to hide their movements from potential threats.
Disruption of Trade Balances
The supply of oil from the Middle East declined after the outbreak of the conflict, but exporters have adapted faster than expected. However, this adaptation has not fully offset the cost pressures that are forcing industrial economies to pay record premiums for crude oil.
High prices may last longer than anticipated given the risk of renewed escalation in the conflict involving the United States, Israel, and Iran. The account indicates that while the market’s return to balance is likely the result of higher non-Gulf oil production and a decline in global oil demand, the remaining deficit in production from the Persian Gulf persists.
Goldman Sachs expects the oil market to shift to a surplus in late 2026 and 2027, which may moderate prices. Struyven predicts the Brent price will average $80 a barrel in 2027, though this forecast assumes continued adaptation of Middle East supply without renewed conflict.
The market’s return to balance is likely the result of higher non-Gulf oil production and a decline in global oil demand, offsetting the remaining deficit in production from the Persian Gulf. In fact, the oil market was nearly balanced in September, with demand exceeding supply by just 0.3 mb/d that month.
Future Outlook and Market Balancing
Oil prices are expected to moderate over the next year as supply from the Middle East gradually recovers, according to Goldman Sachs Research. Struyven maintains their base case that continued adaptation of Middle East supply will eventually reduce crude oil prices, while potential renewed escalation still poses significant net upside risk.
The balance between supply and demand in the global market for crude oil and other liquid fuels will shift to a surplus in the fourth quarter of 2026 and in 2027, the researchers find. This shift represents the key driver of the forecast for crude prices to moderate as the market adjusts to post-conflict realities.
However, the risk of attacks on oil infrastructure like ports, pipelines, and oil fields remains a critical variable that could curtail supply further. If there is an escalation, spot prices for Brent crude include a nearly $25 risk premium because inventories could be drawn down further if the situation deteriorates.
Officials said that the region’s vulnerability to climate change and water scarcity adds another layer of complexity to the energy landscape. Owing to the Middle East’s aridity and pervasive dependence on the fossil fuel industry, it is one of the most vulnerable regions to climate change and water scarcity.
The more Israel seeks military hegemony, the more other states have an incentive to balance against it, according to regional analysts. This dynamic suggests that while supply may recover, the geopolitical friction could continue to introduce uncertainty into global energy pricing mechanisms.
Energy‑Centric Geopolitics of the Gulf Arab States
The cluster of Gulf Arab states that line the Persian Gulf “have vast reserves of petroleum, which has served as a critical economic resource and accordingly influenced regional politics,” according to the regional overview. This petroleum endowment makes the Gulf the backbone of global oil supply, linking the Middle East’s aridity and dependence on fossil fuels directly to worldwide energy security.
Because these reserves underpin both national budgets and international trade flows, any disruption—whether from “dark” exports that hide tanker movements or from threats to ports, pipelines, and oil fields—creates immediate ripples in global markets. The concentration of supply in a few states therefore translates into a strategic lever: the ability of Gulf producers to adjust output can offset broader deficits, while geopolitical tensions can re‑impose risk premiums that lift prices well above fair value.
Sources
- Middle East
- Will Oil Prices Decline as Middle East Supply Recovers?
- Netanyahu map shows Israel’s place among Middle East alliances
Photo: Robert W Watt (CC BY-SA 2.0)